The most useful idea here is that confidence in the AI investment boom can weaken even if artificial intelligence itself proves genuinely transformative. By connecting losses at an AI-focused hedge fund, South Korea’s semiconductor-heavy market decline, rising capital expenditures at Meta, and China’s semiconductor advances, the discussion builds an argument about financial vulnerability rather than simply asking whether AI technology is overhyped. That distinction between technological success and investment success gives the segment considerably more substance than a straightforward bubble warning.
The hedge fund provides an effective opening case because its leveraged strategy concentrates many of the risks the hosts want to examine. A fund that had reportedly produced enormous gains before suffering heavily during July illustrates how leverage can magnify a reversal, while positions in Oracle, AMD, Nebius, Bloom Energy, and Sandisk connect that reversal to the broader AI trade. The hosts reasonably treat this as something worth watching, but calling it the first person to be “wiped out” and presenting the episode as a potential preview of a wider collapse goes beyond what this single example can establish. A leveraged fund experiencing severe losses is evidence of risk, not by itself evidence that an AI bubble is bursting.
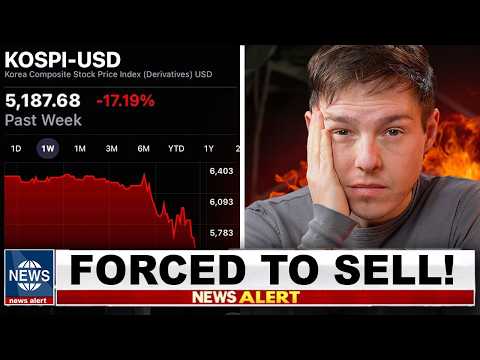
South Korea makes the argument more consequential. The discussion links sharp declines in Samsung and SK Hynix with semiconductor concentration, retail investors using margin, and the possibility that forced selling can intensify an already falling market. That mechanism is clearly explained and helps show why a chip downturn can become larger than the original change in investor sentiment. Yet some of the segment’s most dramatic descriptions—including comparisons with the 1997 and 2008 crises and claims about the scale of the historic collapse—are asserted without enough supporting data or context to evaluate exactly what is being compared.
China is presented as the structural challenge behind these immediate market movements. The hosts point to CXMT and reported progress in domestic DUV lithography as signs that Chinese semiconductor capabilities may be advancing despite export restrictions. They also argue that cheaper, more efficient AI models could challenge a Western strategy built around enormous amounts of compute and expensive data-center expansion. This is a worthwhile connection because it recognizes that competitive pressure could change AI economics even without diminishing the technology’s usefulness. At the same time, the speakers repeatedly move from individual developments to sweeping conclusions about Chinese competitiveness without establishing how close those technologies actually are to replacing the capabilities, supply chains, or models they discuss.
The strongest analytical passage comes when the conversation separates whether AI becomes transformational from whether current companies, spending strategies, and valuations ultimately justify themselves. Those outcomes are not interchangeable, and the segment identifies several plausible combinations: successful technology with successful investments, transformative technology paired with a flawed business model, or broader disappointment on both fronts. The possibility that companies could correctly identify AI as revolutionary while investing in the wrong economic model is a much sharper argument than simply predicting an AI crash.
Meta’s rising capital expenditures and weaker-than-expected financial outlook give that concern a concrete corporate example. The hosts use increased spending on infrastructure alongside pressure on cash flow to ask when enormous AI investments will produce corresponding revenue. They also broaden the potential consequences to data-center construction and related employment, showing how investment retrenchment could extend beyond technology stocks. The weakness is proportionality: phrases suggesting that everything could “go bust completely” or that the economic consequences would be “really dire” are stronger than the evidence presented. The discussion supplies warning indicators, but not enough financial analysis to quantify the probability or scale of those outcomes.
Presentation-wise, the conversational format makes a complicated intersection of leverage, semiconductors, Chinese industrial policy, AI models, capital expenditure, and economic growth relatively accessible. The speakers acknowledge that chip manufacturing and lithography are technically complicated and occasionally qualify their conclusions, including noting that some technology stocks remain positive. Those caveats help, but they compete with repeated “canary in the coal mine” language and increasingly sweeping claims about the broader economy. The result is an engaging and thought-provoking warning about concentrated AI investment, but one whose strongest conclusions would benefit from more comparative market data, sourcing, and technical context before being treated as evidence of an approaching systemic collapse.
Pros
- Clearly distinguishes AI’s potential technological importance from the profitability and sustainability of current AI investment strategies.
- Connects leverage, semiconductor demand, capital expenditure, Chinese competition, and data-center construction into a coherent economic argument.
- The South Korean example effectively explains how market concentration and margin calls can amplify a sell-off.
- China’s semiconductor and AI-model development introduces a meaningful competitive challenge to assumptions behind Western AI spending.
- The speakers include useful caveats, particularly that technology stocks are not uniformly declining and that the underlying technical issues are complicated.
Cons
- Dramatic claims about the historic severity of South Korea’s crash and the possibility of broader economic collapse receive insufficient supporting data or comparative context.
- A severely damaged leveraged hedge fund is treated too readily as a potential signal for the wider AI market without establishing how representative its strategy was.
- Claims about Chinese semiconductor progress and AI efficiency move quickly from specific developments to broad conclusions about Western business models.
- Repeated “canary in the coal mine” framing sometimes makes plausible warning signs sound more predictive than the evidence presented can justify.
- Broader assertions about GDP, consumer conditions, employment, and economic dependence on AI investment are introduced without enough evidence to integrate them convincingly into the market analysis.
The segment identifies a genuinely important question beneath the AI boom: transformative technology does not guarantee that today’s valuations, infrastructure spending, or dominant business models will prove economically sound. Its combination of leveraged losses, South Korean chip exposure, Chinese competition, and escalating capital expenditure makes that risk easy to understand, but the case is strongest as a warning about vulnerabilities rather than evidence that a historic AI collapse has begun.