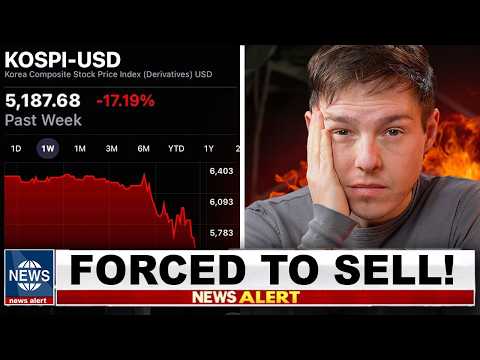
A pair of memory-chip stocks contributing a striking share of one month’s global equity gains provides an effective entry point into a broader problem: investors may be far more exposed to the AI boom than their portfolio labels suggest. From semiconductors and utilities to construction, real estate and private credit, the argument is that AI-related spending has spread deeply enough through markets and the economy that avoiding a handful of famous technology stocks no longer guarantees meaningful distance from the trade. The framing is appropriately conditional rather than apocalyptic, repeatedly emphasizing that a collapse is possible rather than inevitable.
That distinction makes the discussion considerably stronger than a conventional bubble-warning piece. The presentation openly acknowledges the bullish case that AI is a genuinely transformative technology, that companies may ultimately justify enormous infrastructure investments and that investors who have repeatedly predicted technology crashes have often been early or simply wrong. This restraint becomes one of the central ideas: technological importance and investment value are different questions. The railway and dot-com comparisons illustrate that transformative infrastructure can survive and flourish even while the investors who financed an overextended buildout suffer enormous losses.
The examination of diversification is particularly useful because it moves beyond obvious AI holdings. Small-cap indexes can contain rapidly appreciating semiconductor suppliers, while mechanically defined value indexes can end up holding large technology companies after periodic rebalancing. Utilities, construction businesses and data-center landlords can also acquire valuations increasingly tied to continuing AI investment. These examples support the larger contention that owning many securities does not necessarily produce genuine diversification when their fortunes ultimately depend on the same underlying spending cycle.
The estimates of potential losses are dramatic but presented with more care than the headline numbers might initially suggest. Figures ranging into the tens of trillions of dollars are attributed to different analysts and methodologies rather than presented as a single forecast, and the discussion correctly challenges the usefulness of translating aggregate stock losses into an average loss per household when equity ownership is highly concentrated. Still, several large numerical claims arrive quickly and depend heavily on cited outside calculations whose underlying assumptions are not examined in much detail. The result communicates plausible scale more effectively than it establishes a precise estimate of what an AI-driven correction would actually destroy.
More persuasive is the explanation of how falling asset prices could reach people who never owned fashionable technology stocks. The wealth-effect argument connects lower portfolio values to reduced consumer spending, while the discussion of data-center construction extends potential consequences to electricians, contractors, equipment makers and other workers benefiting indirectly from capital expenditure. The private-credit section adds another possible transmission mechanism by arguing that risk may have migrated outside better-capitalized banks. Importantly, the presentation stops short of declaring another 2008 imminent and notes that current private-credit distress remains limited, although the comparison with opaque pre-crisis lending markets occasionally gives the rhetoric more certainty than the available evidence warrants.
Historical comparisons provide the strongest conceptual support. Britain’s railway mania, the dot-com infrastructure boom, Amazon’s enormous drawdown and the disappearance of once-prominent search companies all demonstrate why correctly identifying a technological revolution does not guarantee correctly identifying its profitable investments or buying them at sensible prices. The Amazon example is especially effective because it complicates the comforting idea that simply owning the eventual winner solves valuation risk. At the same time, histories involving different technologies, financing structures and economic environments can only illustrate patterns; they cannot establish that today’s AI investment cycle will follow the same trajectory.
The closing case for genuine diversification is appropriately modest. Rather than recommending wholesale abandonment of American technology stocks, the discussion considers less fashionable European equities as one possible source of lower valuations and different sector exposure while acknowledging that globally diversified investors may need no major change at all. That measured conclusion fits the evidence much better than a crash prediction would. The sponsor interruption is lengthy and breaks the momentum, and some jokes stretch sections that could be tighter, but the overall presentation succeeds because uncertainty remains visible throughout rather than being discarded whenever a frightening statistic appears.
Pros
- Clearly separates the proposition that AI may transform the economy from the separate question of whether current investments are attractively priced.
- Shows convincingly how AI exposure can extend through semiconductors, utilities, construction, real estate, indexes and private credit rather than remaining confined to famous technology companies.
- Treats crash estimates as conditional scenarios and appropriately qualifies misleading household-average calculations.
- Historical examples involving railways, dot-com infrastructure and Amazon effectively demonstrate the difference between correctly predicting a technology and earning attractive investment returns from it.
- Connects potential market losses to the broader economy through consumer spending, employment and capital expenditure rather than treating falling stock prices as an isolated investor problem.
- Avoids making a definitive crash prediction and ends with a restrained diversification argument instead of recommending indiscriminate selling.
Cons
- Several enormous loss estimates depend on outside calculations whose assumptions receive relatively little scrutiny, making the scale easier to understand than the probability or precision.
- Historical parallels are illuminating but sometimes carry more rhetorical weight than their differences from the modern AI market justify.
- Comparisons between opaque private credit today and pre-2008 financial risks can sound more ominous than the acknowledged current default data supports.
- The extended sponsorship segment interrupts an otherwise coherent progression from market concentration to broader economic consequences.
- A large number of statistics, historical analogies and market examples occasionally make the presentation feel denser and more sprawling than necessary.
The argument succeeds because it treats an AI crash as a risk worth understanding rather than an event that can be confidently predicted. Its best insight is that genuine technological progress can coexist with terrible investment outcomes, making valuation and diversification more important than simply identifying the next transformative industry. Some of the largest estimates deserve deeper examination, but the overall analysis is balanced, informative and unusually disciplined about uncertainty.